There has been a lot of geopolitical noise in calendar year 2026. Over the last couple of weeks the discussion has tilted toward the idea that the Indian Stock Market has “held up relatively well” — and now that the noise has abated, “all is well.” This post is about that narrative.
A glance at the Nifty does seem to make us ‘buy the narrative’. I mean, we are within 10 percent of new all-time highs despite the geopolitics. But most of us are asking the wrong question. The Nifty has ‘held up’ — but compared to what? The Nifty against itself?
The right question is how we have done against a relevant peer set. India sits inside the regional Asia Pacific basket — the broad benchmark that holds us alongside Japan, Australia, China, Korea, Taiwan, and others. Here is how that comparison looks.
India numbers are MSCI India (Net) USD. Asia Pacific is MSCI AC Asia Pacific (USD), the broad regional benchmark including Japan, Australia, China, Korea, Taiwan, India. The yellow YTD ’26 column is the FT-anchored gap of more than 25 percentage points; verified against MSCI factsheets and iShares NAV cross-check. The 3-yr Avg is the arithmetic mean of 2023, 2024, and 2025 calendar-year USD returns.
The last calendar year (2025) saw India print +2.6% in USD while peers ran away — South Korea +101%, South Africa +75%, Vietnam +67%, Mexico +56%, Brazil +48%, Taiwan +39%, China +31%. India came last in the basket, by a wide margin. 2026 year-to-date, India is down 8% in USD against an Asia Pacific aggregate up roughly 17% — a gap, in plain words, of more than 25 percentage points. The narrative of “we held up pretty well” is a comforting story; the data is not.
And here’s the inconvenient second fact: India is also the most expensive market in the regional basket at 20.6× trailing earnings, against an MSCI AP average of ~16×. We are charging the highest price tag for the slowest recent print.
Focus on that trailing P/E and on the most recent column. You may disagree with how global allocators behave — but disagreement does not change reality. The reality is what shows up on MSCI factsheets each month, and on those factsheets recency bias rules. Money flows toward markets that just printed well. It does not flow toward spreadsheet projections of where prices should go three years out.
One may also argue that India is a ‘growth story’ and hence the premium — but that seems to suggest we are once again, asking the wrong question. The question no one seems to be asking is this: in spite of the war, capital flows into emerging markets have remained robust — so why isn’t the Indian market getting its share?
Just to be sure, this is not some roundabout manner of saying that FII flows matter — they don’t. I have highlighted this earlier — FII Flows and Indian Stock Market Movements Are Not the Same ‘Ting’ — and I stand by that. But, the fact remains that capital will flow to where it is best treated.
Look at how Indian regulators have treated foreign capital across forty years — Swaraj Paul (1983, blocked from Escorts and DCM by an RBI cap on NRI holdings and LIC’s refusal to register his shares); Christopher Hohn / TCI (2012, ground down at the Calcutta High Court fighting Coal India’s below-market Fuel Supply Agreements that subsidise government power companies); Jane Street (July 2025, ₹4,843 crore (≈$580 million) interim SEBI disgorgement order over alleged expiry-day Bank Nifty manipulation). Different governments, multiple regulators, four decades — same message.
Why would any of these global investors ever attempt to invest in India again? And what kind of “signal” did the regulators inconspicuously send to every other purveyor of global capital watching from the sidelines?
If one were to look for consistency in regulation, it is in the hostility and in the signal that SEBI sends to global investors: India is a regulatory rabbit hole, beware. Forty years of consistently sending the same hostile signal — and by that metric India’s P/E has held up amazingly well. It is a pyrrhic victory. The premium India still commands is structural, not earned — I have walked through one of its mechanisms previously: Price Discovery — Structure drives Volatility in Indian Stock Markets. Foreign capital — think USD — continues to flow out, to destinations that welcome it. Investors are voting with their feet, and so would you, if you were wearing their shoes.
A skeptic might say the current gap is just the Iran war and the energy shock — and they would be partly right. But the trigger is not the cause. Korea and Taiwan absorbed exactly the same shock and printed +101% and +39% in 2025, because their regulators were busy welcoming the global AI-capex flow into local semiconductor capacity. India’s regulators were busy disgorging Jane Street. The shock is what exposed the structural setup. The structural setup is what made the exposure asymmetric.
The standard reflex defence — “yes, but the economy is doing well, GDP growth is strong, the structural story is intact” — is wrong. The reason: the economy does not drive stock prices. Demand and supply do. What the economy can shape is the price-earnings ratio at which capital is willing to clear — and even that ratio is non-stationary — “the market P/E” is not a constant. Put plainly: it’s the regulatory tail wagging the market dog.
#The mechanism — demand is regulation, not economy
Demand for stocks is a function of regulation, not of the economy. Every rupee that finds its way into a secondary market is an allocator deciding this market is the best place to be, weighed against every other place that rupee could have been. The decision is shaped by entry rules, exit rules, tax treatment, dispute resolution, and the speed and predictability of regulatory action. The economy provides the menu of possible returns; regulation decides what is even on the table. The easier it is for a foreign investor to buy Indian stocks, the more demand there will be for them. By throttling capital, the regulator is sending the exact opposite signal — and when better alternatives are visible, the opportunity cost of not being in India shrinks toward zero. At zero opportunity cost, the rational allocator chooses to be elsewhere.
The country multiple is what suffers. And if something is cheaper, the expected value of the bet is higher — isn’t this the very basis of how we allocate our own capital?
Layer the tax regime on top. The Securities Transaction Tax. The Vodafone and Cairn retrospective taxes — settled but never forgotten. The General Anti-Avoidance Rules. Capital-gains tweaks every Budget. Each defensible alone. The cumulative signal is not.
Securities-market regulation globally is a pain — but in India it seems systemic and possibly intentional, and STT revenues do matter to that intention. The direction of travel of foreign capital is a different question from the level of it, and the direction has been clear for some time. India is treated as a tactical allocation, not a structural one.
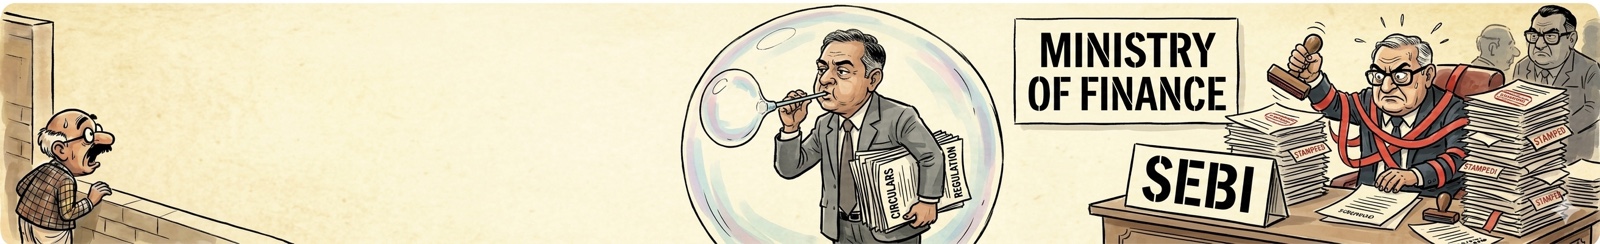
Through MPS rules, IPO sizing, FPI categorisation, derivative position limits, surveillance circulars, and disgorgement orders, SEBI has taken on the responsibility of guiding the market. The aggregate has suppressed small volatility for so long that the only way the underlying market can express itself now is through large, episodic dislocations. This is the regulatory bubble of SEBI’s own making — not a foreign actor, not a global macro event, but the predictable consequence of a regulator that confused the management of information about markets with the management of markets themselves.
Capital is voting with its feet — the vote is not anti-India, it is anti-being-treated-this-way. The establishment has spent forty years treating those as the same thing.
This is how SEBI treats global investors. They have chosen to invest elsewhere. What about local investors — you and me? That’s the next post.
All returns are USD-denominated total returns for cross-market comparability — local-currency returns are obscured by FX. MSCI country/regional index series used where available; iShares ETF NAV (INDA for India, AAXJ for Asia-Pacific cross-check, EEM for EM context) used as second source.
MSCI India numbers are MSCI India (Net Total Return). YTD 2026 cross-checked against iShares INDA NAV.
MSCI AC Asia Pacific numbers are approximate (~) for 2025 and 3-yr Avg — published sources varied; the YTD 2026 cell is anchored to the FT (May 2026) figure of more than 25 percentage points lag versus India.
3-yr Avg is the simple arithmetic mean of the per-year USD returns for 2023, 2024, and 2025 — not a compounded CAGR. Inputs are rounded to one decimal, so the average inherits rounding effects of similar magnitude.
TTM P/E is trailing twelve months, not forward. Source disagreement (MSCI factsheet vs Investing.com vs stockanalysis.com) means single-decimal precision is overconfident; ranges shown where sources disagreed.
Per-country callouts in prose (Korea +101%, Taiwan +39%, etc., for 2025) are MSCI country index USD returns from the same period. Available on request.