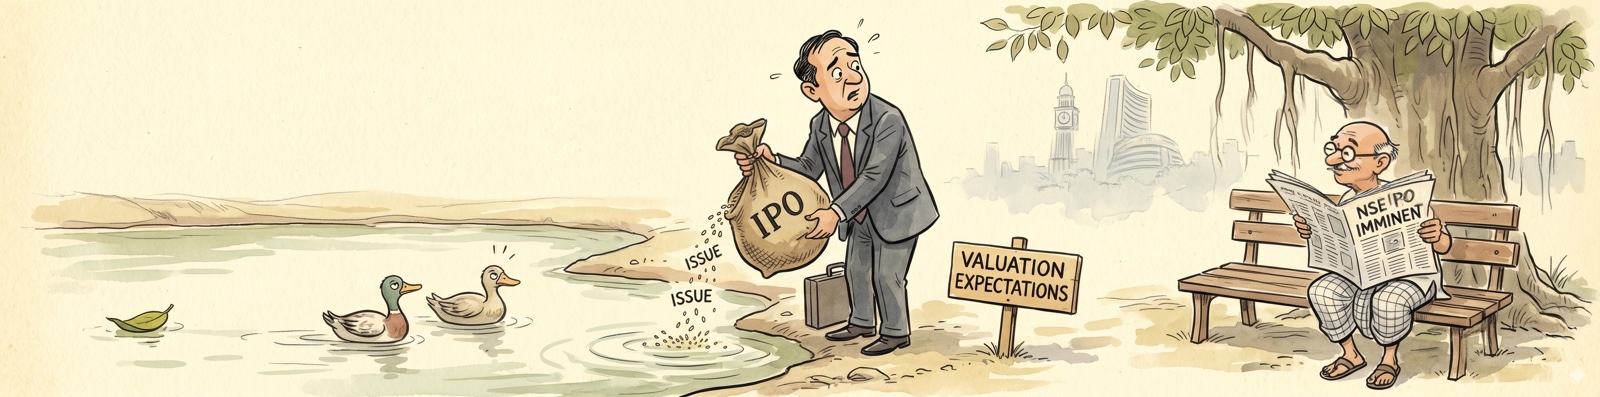
There is a line in investment banking — old enough that no one quite remembers who said it first — that goes: when the ducks are quacking, feed them. When the buyer is loud — retail queueing, oversubscription running, the headline reading “100× covered” — that is the moment to bring an issue to market. Greedy bands, OFS-heavy structures, the lead-manager’s anchor book parcelled out to relationship clients. Feed the ducks.
So what does the regulator do for the you and me — the domestic retail allocator? The IPO is the top of the capital-raising funnel. Equity is permanent capital — no repayment, no maturity, no contractual return — and the price at which it gets raised is, structurally, the high-stakes ground SEBI operates on.
Look at the mainboard IPO calendar between 1 May 2026 and the day this post goes live. Two listings.
For context: the primary market closed CY2025 above ₹1.7 lakh crore. The ducks, briefly, are not quacking. The architecture is, briefly, doing nothing. That brief nothing is the diagnosis.
The architecture assumes the ducks are always quacking. The current silence is what its design looks like with nothing to feed.
SEBI’s measure of success is oversubscription. The Goodhart frame from the previous post carries straight in: when a measure becomes a target, it ceases to be a good measure.
#1. The lull, the pattern, and who is holding the bag
Two mainboard IPOs in six weeks is, frankly, a yawn. The reason cited in every public summary is the same one word: valuation. Issuers want the band 2025 would have cleared. The 2026 buyer will not pay it.
Read across the trade press and you will see a reported pipeline of around 75 mandates with bankers, of which an industry-estimated 40 percent — call it 30 — are expected to clear in the near term. The rest are being deferred, with the same one-word reason. The bankers are not lying. The number is the symptom.
The deeper datum is on the other side of the trade. AMFI’s May 2026 release puts monthly SIP inflows at ₹30,954 crore — the third consecutive month above ₹30,000 crore, up 16 percent year-on-year. The SIP machine is the marginal buyer of every IPO of any size, and the demand it represents absorbed a reported $25.9 billion of FPI outflow through CY2025 with indices barely moving. The first five months of CY2026 have run that pace again.
The rule book the architecture is built on is in plain sight. Every book-built IPO in India runs the same Day-Zero sequence: one working day before retail bids, the lead managers allocate up to 60% of the QIB portion to anchor investors — institutional buyers who commit to a minimum bid of ₹10 crore each. The retail tranche is at least 35% of the issue, with each bid capped at ₹2 lakh per application. When retail is oversubscribed — which it almost always is on any IPO worth participating in — allotment is by lottery, one minimum lot per successful applicant.
There is one detail in this design that I want to underline. You can never qualify as a Qualified Institutional Buyer. Not by entity type, not by capital. A Foreign Portfolio Investor entity with ₹10 crore qualifies; you with ₹100 crore do not. The rule is not about wealth — it is about identity. You are on the wrong side of a glass wall that you cannot walk through, even if you have the bank balance to do so. The rule book draws the line between “retail” and “QIB” categorically, and the line will not move.
That is the entry side. The structure underneath it is what plays out when the rent is on offer — and the canonical illustration from the CY2025 listing class is Hexaware Technologies.
Hexaware was taken private by the Carlyle Group in 2020. The IPO five years later was the exit. The facts, in one table:
The seller had its liquidity event on Day Zero — the day retail’s bank accounts were debited. Retail allotted by lottery, after the ₹2 lakh cap, sat through the drawdown.
Read the sequence the way the architecture wrote it. Institutional capital got a one-day informational advantage on anchor day. Sixty percent of the QIB tranche was allocated to it under lead-manager discretion through Schedule XIII. The seller converted otherwise-locked equity into cash on listing day via the OFS route. Anchor unlock windows opened at 30 and 90 days. Retail held what was left.
That structural pattern is what plays out as the architecture is designed. The mechanism does the work; no rule book needed.
The carve-out manufactures clearing demand, the OFS converts insider equity to cash, the lock-in hierarchy gives the latest-arriving capital the fastest exit, and retail is left holding what each prior tier exited. It is the architecture working as intended. And, the architecture is designed in such a manner that retail might as well be called ‘bag holder category’!
#The rule book is the receipt
Regulation 16 of SEBI’s ICDR Regulations 2018 sets the lock-in periods — how soon each class of allottee can take cash off the table — and Regulation 17 the inscription and release mechanics. Here is the entire framework, in one table:
The order in which capital can exit an Indian IPO is the inverse of the order in which it took risk.
And the locks above apply only to the remaining shares an existing holder did not offload in the IPO itself. Carlyle in Hexaware sold ₹8,750 crore in the OFS and held nothing back. There is no lock-in on cash.
#2. SEBI’s mandate — being followed, or being gamed?
Section 11(1) of the SEBI Act 1992:
“Subject to the provisions of this Act, it shall be the duty of the Board to protect the interests of investors in securities and to promote the development of, and to regulate the securities market, by such measures as it thinks fit.”
In 2009 the regime needed foreign capital. In 2026 it does not.
Three duties — protect investors, develop the market, regulate the market — and the regulator is required to weigh them. The 2009 anchor framework was, openly, a development intervention with an acknowledged cost to investor protection. In 2026, the development case has retired itself. The investor-protection cost has not.
SEBI’s own September 2024 study on IPO investor behaviour documented that 54 percent of non-anchor IPO shares, by value, were sold within one week of listing — retail loss-taking, by the regulator’s own data, inside the architecture the regulator designed. The same study, conspicuously, did not present anchor-versus-retail post-listing returns side by side. The regulator that has all the data did not present the one comparison that would settle the question. Make of that what you will.
And the 31 July 2025 consultation paper proposes — for issues above ₹5,000 crore — to deepen the development side (QIB 50 to 60 percent) and cut the investor-protection side (retail 35 to 25 percent), in exactly the regime that obsoleted the case for either move.
That is not three duties being weighed. It is one duty firing at the cost of another, with the regulator’s own data on the record and the next round of cuts already drafted. The mandate is not being followed. It is being gamed. Creating scarcity, privatising liquidity, and the egregious price discovery that follows from both — Section 3 below takes them apart in detail — is not what Section 11(1) authorises. The architecture engineers all three anyway, at the cost of the very investor the mandate exists to protect. The architecture doesn’t just allow retail to lose money. It is the mechanism by which they do.
#3. Where price discovery actually happens
Price discovery is the most difficult and most important part of any IPO. Globally there is no unanimity on the best mechanism for doing it — Section 4 below takes up the alternative this post lands on. This section is about why the Indian mechanism, as currently designed, fails the job.
The institutional defence is that the anchor carve-out does the discovery work — without committed institutional demand at the front of the book, the band would lack credibility and the issue would risk failure. The defence has three pieces. Each fails.
On liquidity, the carve-out does not enhance liquidity. It privatises it. The two most liquid windows in an IPO — anchor day and listing day — are reserved for institutional capital. The retail subscriber, who is the marginal buyer of the post-listing trade, has no allocation lever on the day price is set, and no informational lever on the day the order book is built.
On scarcity: the principle is not new. Identical goods attract higher willingness-to-pay when supply is restricted — desire is shaped by both hedonics (how good the thing is) and exclusivity (having what others cannot). Scarcity, in plain English, is the load-bearing variable in retail bidding behaviour. Is that rocket science?
The IPO mechanic puts the principle to work at industrial scale. With a ₹2 lakh retail cap, lottery allotment, and a retail-tranche-to-demand ratio fixed by the regulator, the 50 to 100 times oversubscription figure is a mathematical guarantee — not a market signal. The architecture is designed to produce that number, and then the same number is cited as evidence that the architecture is “working.”
And the receiving end of that engineered scarcity is the retail subscriber. Forty thousand applicants, fifteen lots, one minimum bid each. The same SEBI that has decided you cannot apply for more than ₹2 lakh of exposure has also decided that even within that cap, you are picked by random number generator. You cannot bid up. You cannot earn priority through track record. You cannot stand in line. The rules turn you into a roulette chip.
On price discovery itself, in a 50 to 100 times oversubscribed market — before anchors commit — the price has already been discovered by SIP-side demand. The anchor is not discovering price. The anchor is collecting rent on the spread between the price the SIP buyer would have cleared at and the strike the band locked in. That spread is the listing pop. It is not a discovery. It is a transfer.
And the cleanest piece of evidence is the lull itself. If the carve-out were doing genuine discovery, it would not exist; issues would clear because the architecture guarantees clearing. The lull is the architecture’s discovery function being replaced, in plain view, by its extraction function. When the rent is not on offer, the machine stops.
The “without anchors, retail gets hurt worse” line was true in 2009. It is doing different work in 2026.
#4. The way out — Dutch auctions
If the carve-out is no longer doing the discovery work, what does? Globally, the cleanest alternative is the Dutch auction.
The advantages are three. There is no listing-pop spread by construction — every successful bidder, institutional or retail, pays the same clearing price. There is no allocation discretion — no Schedule XIII, no relationship-favour pick. And the discovery is ex ante, by competitive bid, rather than ex post, by insider allocation and listing-day rent.
The bankers’ counter has always been the same line: retail wouldn’t price competently. This is the rent rationalised. In a market where retail SIPs absorbed roughly $25.9 billion of FPI exit through CY2025 with indices barely moving, and where clearing demand is — on the regulator’s own oversubscription number — manifestly not the binding constraint, the retail-can’t-price defence is a self-serving claim about a buyer the architecture has rendered indispensable.
The warning the post closes on is forward-looking.
NSE’s own IPO has been pending since the exchange first filed for a listing nearly a decade ago and withdrew. SEBI’s no-objection certificate was issued on 30 January 2026; the NSE board approved the plan on 6 February; the DRHP is reportedly expected by June 2026, listing reportedly targeted before December at ₹22,000–₹23,000 crore, reportedly a pure OFS. Reliance Jio’s DRHP is reportedly imminent on the press reporting available mid-June 2026 — not on SEBI or stock-exchange records as of writing — at a structure reportedly shaped as a fresh issue of around ₹25,000 crore, with industry-estimated valuation bands in twelve-figure US dollar territory.
If either of these lists under the rule book the consultation paper proposes — retail 25, QIB 60, Schedule XIII discretion intact, OFS route open, anchor architecture untouched — the structural value transfer this post has named will be channelled through the two largest issues in the country’s history, on the largest retail demat base it has ever had.
The honest response is to fix the architecture first, and bring NSE and Jio after. The 2009 rule book is not an heirloom. The market it was built for is gone.
The ducks are not quacking. The architecture has stopped doing the work it was designed to do — and that is the moment to ask, finally, what it should have been doing all along.
#Notes on the data
- Mainboard IPO calendar, 1 May – 14 June 2026. Two listings: CMR Green Technologies (₹630.62 cr, listed 10 June 2026) and Hexagon Nutrition (₹139 cr, listed 12 June 2026). Aggregate under ₹800 cr. Sources: Chittorgarh IPO calendar, BSE/NSE listing pages, Goodreturns and Business Standard reporting.
- Pipeline figures. The “~75 IPO mandates currently with bankers” figure is an industry estimate cited in trade press through May–June 2026; not directly published by SEBI. The “~40% / ~30 of 75 expected to clear in the near term” figure is from the same reporting and is labelled “reported / industry-estimated” inline. Independently verifiable data point: 144 companies with SEBI approval targeting ~₹175,000 cr, plus 63 firms targeting ~₹137,000 cr awaiting clearance (Business Today / Subkuz, May–June 2026 reporting).
- AMFI monthly SIP inflow. ₹30,954 cr in May 2026 — the third consecutive month above ₹30,000 cr. Year-on-year up 16% from May 2025’s ₹26,688 cr. Source: AMFI monthly data release, May 2026.
- FPI outflow figures. Calendar 2025: net ₹2.16 lakh cr (~$25.9 bn) — the highest annual FPI outflow on record (Outlook Business, Business Standard). 2026 year-to-date pace already exceeding 2025 within five months. The earlier “$53 bn over 18 months” framing carried from prior research is reported (paraphrased from Aiyar’s column) and softened in this post to the verifiable pair “$25.9 bn in CY2025” + “comparable scale year-to-date 2026.”
- Hexaware Technologies IPO. Issue dates 12–14 Feb 2025, listed 19 Feb 2025. Issue price ₹708 (upper band of ₹674–₹708). 100% OFS by CA Magnum Holdings (Carlyle Group affiliate) for ₹8,750 cr. Listed at ₹745.50 — 5.3% premium. 52-week low ₹592.95 on 7 April 2025 (between the 30-day and 90-day anchor unlock dates, roughly 16% below issue). 52-week high ₹900.15 on 9 July 2025. Specific unlock-day closing prices not surfaced by reliable sources at the time of writing — claim held to the between-unlock-dates drawdown that is verifiable, rather than a specific unlock-day move.
- SEBI Act 1992, Section 11(1). Quoted verbatim from the operative text on sebi.gov.in / IndianKanoon.
- SEBI September 2024 IPO investor behaviour study. 54% of non-anchor IPO shares (by value) sold within one week of listing, across 144 mainboard IPOs listed April 2021 – December 2023. Source: SEBI Press Release, September 2024.
- SEBI 31 July 2025 consultation paper. Consultation Paper on Facilitating Ease of Doing Business relating to Anchor Investor Allocation, Long-Term Institutional Participation and Retail Quota in IPOs under ICDR Regulations 2018. For issues > ₹5,000 cr: retail allocation proposed 35 → 25%; QIB allocation proposed 50 → 60%. Public comment closed 21 August 2025. Source: sebi.gov.in.
- Dutch auction precedents. Google (Aug 2004): $85 strike, $100.34 Day-One close, ~18% pop — SEC filings, contemporaneous press. Morningstar (May 2005): $18.50 strike, $20.05 close, ~8% pop — Morningstar press release. Interactive Brokers (May 2007): $30.01 strike, $31.30 close, ~4% pop — SEC FWP filings, TheStreet. NetSuite (Dec 2007): $26 strike, ~25% Day-One run-up — Fortune, Techdirt.
- NSE IPO status (as of 14 June 2026). SEBI no-objection certificate 30 Jan 2026. NSE board approval 6 Feb 2026. DRHP reportedly expected June 2026. Listing reportedly targeted before December 2026. Issue size reported at ₹22,000–₹23,000 cr. Reported as pure OFS. Labelled “reported / expected” — DRHP not on the SEBI public record at the time of writing.
- Reliance Jio IPO status (as of 14 June 2026). DRHP filing reported as imminent — week of 15 June 2026 per IPOWatch / Multibagg — but not on the SEBI public record at the time of writing. Structure reported as ~100% fresh issue of ~₹25,000 cr. Labelled “reported / expected” throughout.
- Goodhart frame. Carried forward from the predecessor post — SEBI Is in a Regulatory Bubble of Its Own Making, vimalsons.com/blog/sebi-regulatory-bubble/ — where the formulation “when a measure becomes a target, it ceases to be a good measure” set the spine. Used here as the framing for the lull-as-diagnosis observation.