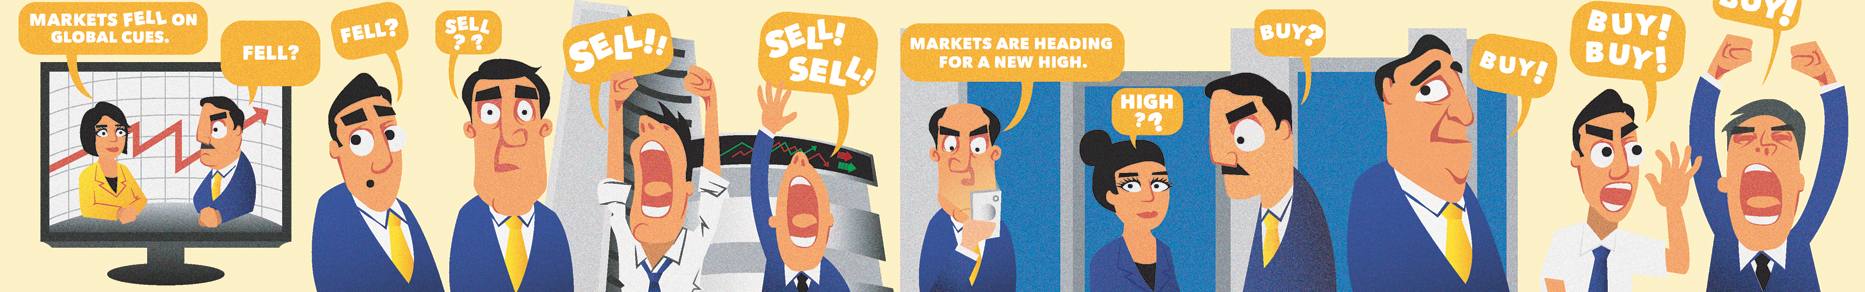
All of us try and time every decision we make (be it a financial one or otherwise); and by definition that means we are going to try and time our trades. When we get the timing accurate, we are fooled by randomness, and end up thinking that we will continue to do so in the future as well.
When we decide to buy a stock, what we are doing is expressing an opinion about the market, not about the stock that we propose to buy. The perceived wisdom is “as goes the market, so go all the stocks in the market.” Reality proves this assumption to be ab initio incorrect. Many stocks diverge from the overall market trend (Dispersion). So, the timing game is two fold — the first part is expressing an opinion about the overall direction of the market and the second is expressing an opinion about the direction of the stock that we want to invest in. Most, nee almost all, investors tend not to understand the nuance.
If you want to emulate Buffett, his words are: “If we’re right about a business, and we think it’s attractive, it would be very foolish for us to not take action because we thought something about what the market was going to do or anything of that sort. Because we just don’t know.”
So, the idea is to invest in a good business, and not bother about the opinions of anyone else, and not heed to one’s behavioural biases. Once you’ve identified a good business, the timing of the actual buy trade doesn’t matter all that much, as long as one has a time horizon of a decade, at the very least.
Sticking with Buffett, this nugget from an interview of Bryan Lawrence is of immense value:
“When I started Oakcliff in 2004, I was lucky enough to find myself in a room with Warren Buffett and two dozen other aspiring stock pickers. We were very happy to ask him lots of questions, which pretty much all boiled down to, ‘How do we get to be like you but faster.’ He very nicely broke to us the bad news that stock picking was a long game, but he said, ‘I do have a piece of good news for you, the average stock goes up and down by 80% in a year. And that’s an enormous advantage if you actually take the time to understand the underlying business because the stock price is not reflecting underlying value if it’s going up and down by 80%.’”
“I said to myself, ‘80% in a year, he’s got to be out of his mind. He’s Warren Buffett, but he’s lost his mind.’ I went back to New York, and I did the calculations he was suggesting, which was to compare the 52-week high to the 52-week low for every stock in the stock market and compare the percentage difference between those two things. And when I did the calculations, maybe not surprising because he is the Sage of Omaha, he was right.”
So, there you have the HOLY GRAIL of ‘Market Timing’ — building the PATIENCE to wait for the inevitable swing in market prices. This actually resonates with what Seth Klarman has said: “You must buy on the way down. There is far more volume on the way down than on the way back up, and far less competition among buyers. It is almost always better to be too early than too late, but you must be prepared for price markdowns on what you buy.”
Nicolai Tangen is the CEO of Norges Bank Investment Management, Norway’s $1.4 trillion sovereign wealth fund. This nugget from him has immense wisdom: “The way to judge yourself is inertia analysis. Run your January 1 portfolio for the full year without any changes and compare it to your actual results. It’s awful because some years you realize all you did was subtract value when you went into the office.”
The question to ask might be: Would being inert, and not trading at all be better than ‘timing’ one’s trades? A portfolio tilted toward a diverse basket of stocks provides the engine for long-term growth. Yet, investors have a knack for over-complicating investing by trying to do too much. David Swensen (who wrote Pioneering Portfolio Management), described these tools as asset allocation, market timing, and security selection. Market timing and security selection are a net negative on portfolio returns. Emotions are the main culprit. Asset allocation works best when it’s left alone.
Many investors attend ‘stock market training classes’ which preach the use of Technical Analysis (TA) as THE ultimate tool for timing trades. The problem is that TA only shows the past and the assumption is that the future will repeat as it has in the past, but what if it doesn’t?
The final word on this topic comes from James Montier (a behavioral finance specialist and Senior Advisor to GMO): “One of the most useful things I’ve learnt over the years is to remember that if you don’t know what is going to happen, don’t structure your portfolio as though you do!”
